
2026 Half-Year Results
Strong acceleration in growth and profitability in line with the business plan
The 2026 half-year financial statements are presented on a consolidated basis, unlike the comparative figures for the first half of 2025, which were prepared on a company-only basis. They were approved by the Board of Directors on September 23, 2026, and the auditors’ report is currently being issued.
Consolidated half-year results: EBITDA of €5.0 million, representing 7.0% of revenue
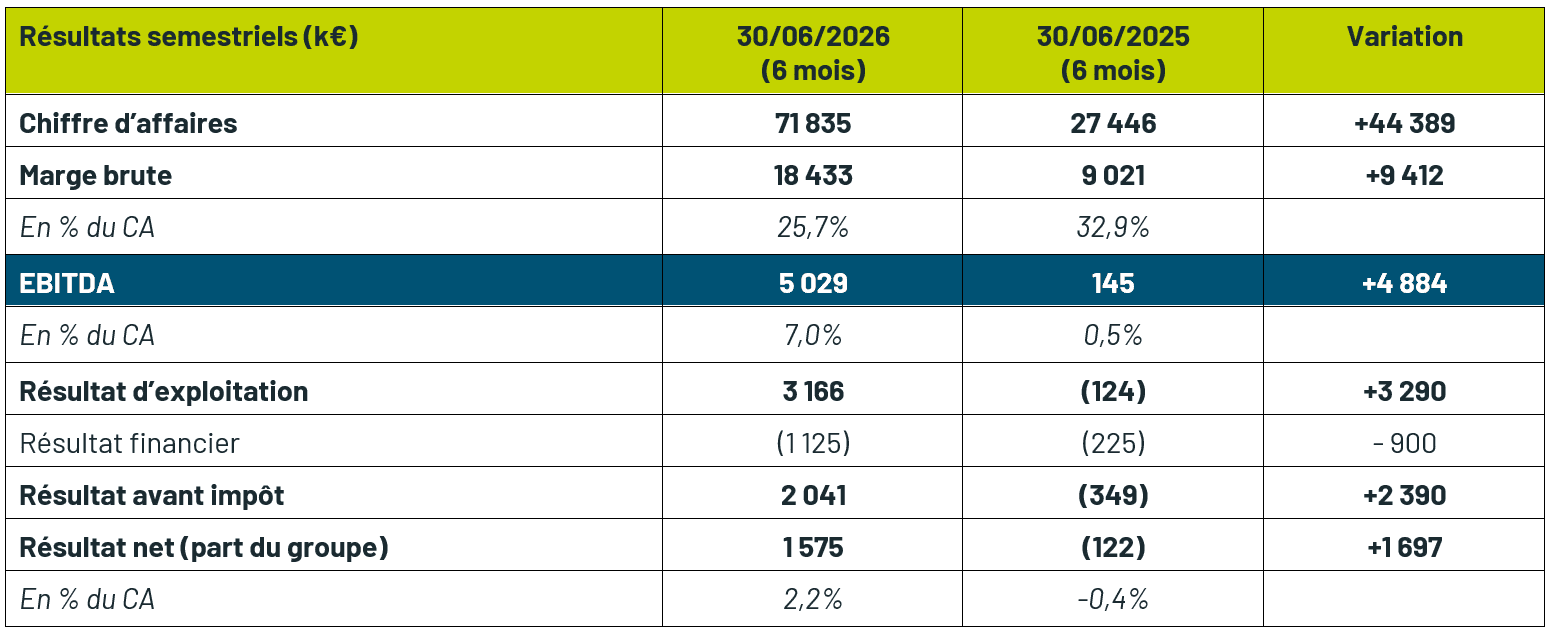
Consolidated revenue for the first half of 2026 totaled €71.8 million, compared with €27.4 million in the first half of 2025, on a comparable basis between the two six-month periods. This increase reflects the recognition of revenue based on the percentage of completion of the record order backlog built up in 2025.
Growth was driven by the Entech Construction business: ground-mounted solar power plants reached €28.2 million (+248%) and energy storage projects €34.3 million (+216%), including €12.7 million from the company’s share of the joint venture established with Eiffage Énergie Systèmes. Entech Solutions posted more modest growth, reaching €8.3 million (+6.3%), driven by rooftop and shade structure solar power plants (€7.5 million). Entech Energy & Services, which is in its start-up phase, generated €0.2 million.
Gross profit totaled €18.4 million, up 104%, or €9.4 million more than in the first half of 2025. It represented 25.7% of revenue, compared with 32.9% in the first half of 2025—a change of 7.2 percentage points due to the product mix effect: the very strong ramp-up of EPC (engineering, procurement, and construction) activity on large-scale projects automatically lowers the average gross margin rate, while generating a significantly higher volume of EBITDA.
EBITDA came in at €5.0 million, or 7.0% of revenue, compared to €0.1 million (0.5% of revenue) a year earlier, including a contribution of €0.3 million from the joint venture established with Eiffage Energie Systèmes. In just one half-year, the Group’s EBITDA thus exceeded that of fiscal year 2025 (€4.4 million), and the EBITDA margin is already on track to meet the 8% to 10% target set for the fiscal year.
This performance reflects the targeted operational leverage: personnel expenses totaled €8.9 million, up 44%, but now account for only 12.4% of revenue, compared with 22.6% in the first half of 2025 (and 16.1% for the full year 2025). The average headcount for the first half of 2026 was 222 FTEs (Full-Time Equivalents), compared with 161 FTEs in the first half of 2025. Other operating expenses rose by 58% to €3.8 million, representing 5.2% of revenue, down from 8.7%. The group is now structured to support the ramp-up of its operations without a proportional increase in its cost base.
After €2.4 million in depreciation, amortization, and provisions, operating income came in at €3.2 million, compared to a loss of €0.1 million. Net financial income amounted to -€1.1 million, compared to -€0.2 million, reflecting an increase in debt intended to finance the growth of the EPC business and the development of the portfolio of assets held for own use (Entech Energy & Services). Net income attributable to the Group amounted to €1.6 million, compared with a loss of €0.1 million in the first half of 2025.
Financial Structure: Growth That Generates Free Cash Flow
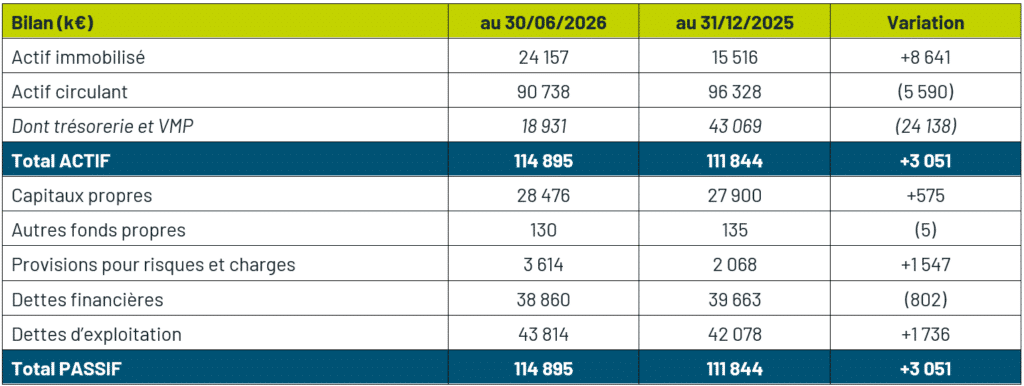
Shareholders’ equity totaled €28.5 million as of June 30, 2026, an increase of €0.6 million. Fixed assets increased by €8.6 million (+56%), primarily due to an increase in property, plant, and equipment (+€8.2 million), reflecting investments made in the portfolio of assets owned by Entech Energy & Services and changes in the scope of consolidation during the half-year (€7.9 million).
Cash flow from operations reached €4.3 million, compared to €0.5 million in the first half of 2025, converting approximately 78% of the increase in EBITDA into cash flow from operations. Working capital requirements, however, totaled €18.3 million for the half-year, driven by business growth: accounts receivable increased by €12.5 million (+37%) in line with the pace of project progress, while accounts payable rose by €14.8 million.
Cash and marketable securities therefore totaled €18.9 million as of June 30, 2026, compared with €43.1 million as of December 31, 2025, the latter figure having benefited from exceptional customer prepayments at the end of the previous fiscal year prior to the disbursement of supplier prepayments in early 2026. Financial liabilities remained stable at €38.9 million. Net financial debt thus stood at €19.9 million, compared to a positive net cash position of €3.4 million as of December 31, 2025.
As announced on December 18, 2025, Entech has had access to €60 million in syndicated credit facilities since the beginning of 2026, enabling the group to finance its continued growth.
Orders Received and Backlog[1]
In the first half of 2026, the Group recorded €45.8 million in new orders, notably including the signing of new battery storage contracts. The half-year was also marked by the launch of two international projects, both carried out as part of a consortium, which are the largest storage projects ever undertaken by the Group.
The consolidated backlog as of June 30, 2026, stood at €116 million, compared to €150 million as of December 31, 2025, as the revenue generated from the order backlog built up in 2025 exceeded new orders received during the half-year. When added to revenue already recognized, this order backlog represents €188 million, which more than covers the €130 million target set for the fiscal year.
Perspectives: Confirmation of the 2026 Goals and the 2029 Roadmap
Based on the results of the first half of the year, Entech reaffirms its 2026 target of €130 million in revenue, coupled with an EBITDA margin of between 8% and 10% of revenue.
Priorities for the second half of the year include maintaining the gross margin, managing working capital requirements, consolidating the operational leverage achieved on EBITDA, and continuing to expand the Entech Energy & Services portfolio.
The Group confirms its strategic roadmap through 2029, targeting revenue exceeding €300 million with an EBITDA margin of 20 to 25 percent, including ownership of a portfolio of more than 350 MW of assets in operation or under construction.
[1] Backlog: Revenue Yet to Be Earned